
A core banking system can continue processing transactions long after it has stopped serving the institution well. That shouldn’t surprise anyone; it’s the reality we see daily in many microfinance institutions.
For a microfinance bank, the warning signs usually surface gradually as staff find themselves reconciling transactions manually while regulatory reporting devolves into heavy spreadsheet work. Connecting a basic mobile app becomes a major technical project. Support issues drag on longer than they should, eventually turning the core into a persistent hurdle the team simply works around.
At that point, changing systems becomes a serious business decision.
For executives comparing Seabaas Lite and other mfb core banking systems, the evaluation goes beyond a standard feature list. An MFB must look at the hidden work a core creates around itself. This involves implementation effort, infrastructure demands, daily operational overhead, and what actually happens when the bank scales.
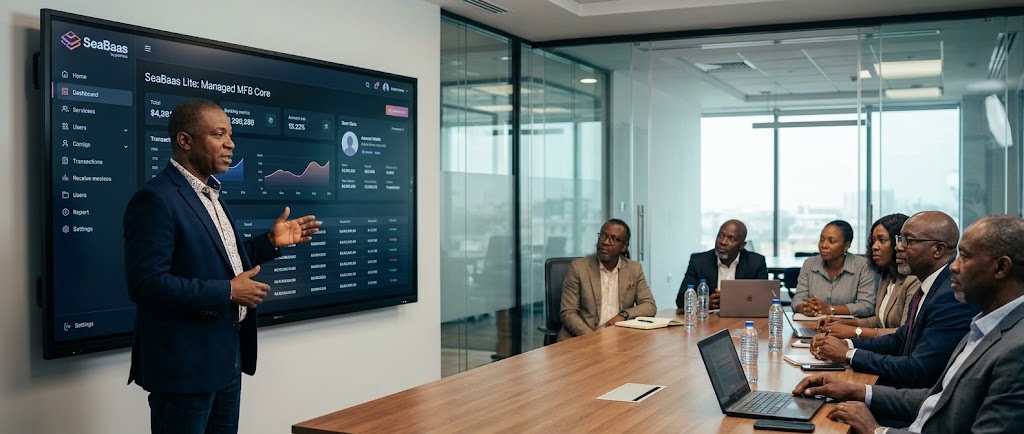
SeaBaas Lite was built for this context. It is a streamlined SaaS version of the SeaBaas platform designed for microfinance banks, digital lenders, cooperatives, fintechs and growing financial institutions that need modern core capabilities without the complexity of a full enterprise deployment.
This comparison looks at where that approach differs from the kind of legacy core environment many MFBs are trying to move away from.
SeaBaas Lite vs Legacy MFB Core Banking Systems at a Glance
Legacy systems differ, so no comparison can fairly describe every older platform in the same way. Some have been upgraded significantly over the years. The table below focuses on common issues institutions encounter in older MFB core environments.
| Area | Typical Legacy MFB Environment | SeaBaas Lite |
|---|---|---|
| Delivery model | May depend on locally maintained servers and infrastructure | Fully managed SaaS model |
| Architecture | Older or tightly connected application structure may limit change | Built on the modern SeaBaas architecture |
| Integration | Integrations may require bespoke work or middleware | API-first integration architecture |
| Digital channels | Connectivity depends on existing interfaces | Designed to integrate with mobile apps, payment rails and fintech services |
| Product setup | Product changes may require vendor intervention depending on the system | Pre-configured core with product and operational capabilities |
| Regulatory reporting | Manual or fragmented reporting may remain common in older environments | Local regulatory reporting templates |
| Analytics | Reports may depend heavily on extracts and spreadsheets | Built-in analytics and real-time dashboards |
| Infrastructure | Institution may carry hardware and maintenance responsibility | Managed cloud deployment |
| Support | Depends heavily on vendor location and service structure | Local technical and customer support |
| Scaling | Growth may increase infrastructure and maintenance complexity | SaaS infrastructure designed to support institutional growth |
The real value of this comparison becomes clearer when each difference is connected to an everyday MFB problem.
So, what exactly should MFBs compare when looking at SeaBaas lite and other MFB core banking systems?
1. Infrastructure: How Much Technology Does the MFB Need to Manage?
Many microfinance banks operate with relatively small technology teams. That makes infrastructure overhead particularly important. When an institution has to manage servers, backups, software dependencies, upgrades and the core application itself, internal teams can spend a large amount of time keeping the environment running.
Older core deployments may still depend heavily on institution-managed infrastructure. That arrangement can work, but it also places more operational responsibility on the MFB.
SeaBaas Lite uses a fully managed SaaS model hosted on cloud infrastructure, with Nigerian data residency for its Nigerian deployment.
This changes the operating model for the institution. The MFB can focus more of its internal technology capacity on channels, customer experience, integrations and business requirements instead of carrying the same level of infrastructure management.
For organisations assessing Seabaas Lite and other mfb core banking systems, this should form part of the cost discussion. The licence price alone does not show how much effort the institution will spend maintaining the environment.
2. Integration: Can the Core Connect Easily to the Rest of the Business?
An MFB may start with branches and a core system, but growth usually increases the number of systems around that core. Mobile banking may be added. USSD may follow. The institution may need NIBSS and NIP connectivity, identity verification, agency banking, card processing, credit bureau services, accounting systems or another fintech partner. The quality of the integration layer then becomes a business issue.
An older core can support these connections, but legacy implementations sometimes depend on custom middleware, manual processes or interfaces created for individual use cases. Each additional integration can increase technical dependency.
SeaBaas Lite retains the API-first integration architecture of the wider SeaBaas platform. It is designed to connect with services such as:
- Mobile banking applications
- Payment switches including NIBSS and NIP
- Agency banking platforms
- Card processors
- National payment rails
- Credit bureaus
- BVN and NIN verification services
- Third-party fintech services
- ERP and accounting platforms
SeaBaas Lite exposes RESTful APIs and supports webhook events for approved third-party connections.
The practical question for an MFB is therefore straightforward: how difficult will the next integration be?
A core that supports easier connectivity gives the institution more freedom to develop its digital ecosystem after implementation.
3. Reporting and Regulatory Work: How Much Manual Effort Remains?
Regulatory reporting is one area where weaknesses in a core system quickly become visible. When staff need to pull records into spreadsheets, combine information from different places, make repeated adjustments and manually validate reports, compliance work becomes expensive in staff time.
The same problem affects management reporting. Executives may wait for teams to compile information before they can understand deposit movement, lending performance or operational activity.
SeaBaas Lite includes pre-configured reporting templates aligned with local requirements, alongside audit, reporting and end-of-cycle capabilities.
The platform also provides operational dashboards and analytics. This matters when comparing Seabaas Lite and other mfb core banking systems because reporting cost rarely appears clearly in a software quotation.
An institution should calculate the hours its finance, operations and compliance teams currently spend preparing, correcting and reconciling reports. That is part of the real cost of the existing core.
4. Customer and Account Operations
Microfinance banking involves a large number of routine operational activities. The core must handle customer records, branches, permissions, accounts, transactions, fiscal periods, restrictions, charges, taxes and accounting accurately.
SeaBaas Lite includes a defined package of essential banking components:
| Capability | What It Supports |
|---|---|
| Customer Management | Customer creation, records and onboarding workflows |
| Customer 360 | Consolidated customer visibility across accounts and relationships |
| Branch Management | Branch setup and operational management |
| User and Role Management | User access and permissions |
| Chart of Accounts | Ledger structure and accounting |
| Currency Management | System currency setup and management |
| Branch Transactions | Banking and payment activities |
| CASA Product Factory | Deposit product definition |
| Charges and Taxes | Configuration and application of charges and taxes |
| Account Restrictions and Controls | Account-level restrictions |
| Fiscal Period Management | Management of system fiscal cycles |
| Audit, Reporting and EOC | Activity tracking, reporting and end-of-cycle processing |
SeaBaas Lite deliberately uses a more standardised model than full SeaBaas. That distinction is important to point out.
Smaller financial institutions may not need the configuration depth and implementation complexity required by a large commercial bank. They may benefit more from a defined core package that covers the essential operating model and can be deployed with less customisation.
5. Data and Operational Visibility
Growing an MFB without clear operating data makes management harder. Leadership needs to understand deposits, loan performance, liquidity, customer activity and transaction behaviour. Operations teams need to identify exceptions quickly. Finance needs information it can reconcile. In older environments, this visibility may depend heavily on static reports or spreadsheet analysis.
SeaBaas Lite includes an analytics layer with dashboards designed to provide visibility into areas such as deposits, lending and transaction activity. Customer 360 also gives teams a consolidated view of a customer across accounts and products.
This does not automatically create better business decisions. People still need to interpret the information correctly. However, making data available sooner gives management a stronger starting point than waiting for several manual extracts to be assembled.
6. Support: What Happens When Something Goes Wrong?
Support quality has an outsized effect on smaller financial institutions. An MFB may not have a large internal engineering organisation capable of diagnosing every issue independently. When something affects transactions, reporting or customer service, the institution needs access to people who understand both the platform and the environment in which it operates.
SeaBaas Lite provides locally grounded technical and customer support. Its support structure includes a dedicated Customer Success Manager, a technical support desk, defined escalation paths, product update communication and an SLA framework.
That becomes an important point when assessing Seabaas Lite and other mfb core banking systems. Before selecting a vendor, an MFB should ask:
- Who receives a critical incident?
- Where is the support team located?
- How does escalation reach engineering?
- What happens after implementation ends?
- How are product and regulatory updates communicated?
- What level of support sits inside the commercial agreement?
A system can perform well for months. The real quality of the vendor relationship often becomes clear on the difficult days.
7. Implementation: How Quickly Can the Institution Become Operational?
Migration time affects cost. Long projects require staff attention, consultancy effort, testing resources and management involvement. Delays can also affect product launches or market-entry plans. SeaBaas Lite uses a structured implementation model designed for a focused deployment.
A typical journey includes:
- Environment setup: cloud provisioning, system configuration, security and access setup.
- Product configuration: account and loan product setup, charges, taxes and integrations.
- Training and UAT: administrator and operations training, user acceptance testing, documentation and process guides.
- Go-live preparation: data migration, parallel run where required, live monitoring and hypercare.
The indicative streamlined journey can move toward go-live from around week five onward. Actual timelines depend on data complexity, integration requirements, institutional readiness and project scope.
That qualification matters. No serious core provider should promise the same implementation duration for every MFB. A bank with clean data and limited integrations is a different project from one migrating years of inconsistent records and several connected systems.
8. Cost: Look Beyond the Subscription Fee
Price is understandably important for an MFB. However, software cost should include everything required to operate the core successfully.
Consider the following:
- Subscription or licence fees
- Infrastructure
- Implementation
- Integrations
- Support
- Internal technical resources
- Reporting effort
- Upgrade costs
- Manual reconciliation
- Future change requests
SeaBaas Lite uses a SaaS model with flexible, growth-aligned pricing. It is designed to remove some of the infrastructure and deployment complexity associated with traditional enterprise core systems.
This does not mean every institution will automatically spend less. Scope and requirements still determine the commercial case.
A useful TCO assessment should compare the current annual cost of the existing environment with the expected cost of running the new one over several years. That gives management a much more useful number than comparing software prices in isolation.
9. Scalability: What Happens When the MFB Grows?
The core selected by a small MFB should not become the reason it struggles when customer and transaction volumes increase. Growth can come from new branches, stronger digital acquisition, agency banking, partnerships, larger lending portfolios or new product lines. Each one puts additional pressure on infrastructure.
SeaBaas Lite is built on the same underlying modern architecture as SeaBaas and is designed to support growing institutions through its cloud SaaS model.
It also inherits the wider SeaBaas platform’s engineering foundation. Current approved SeaBaas proof metrics include more than 20,000 TPS at peak, 871 TPS average throughput and 99.95% availability.
These are SeaBaas platform metrics, so an MFB should not interpret them as a guaranteed individual SeaBaas Lite performance level. Capacity and service commitments should always reflect the institution’s agreed deployment and SLA. Still, they provide useful evidence about the platform family on which SeaBaas Lite is built.
Which Institutions Are a Good Fit for SeaBaas Lite?
SeaBaas Lite is designed primarily for institutions that need modern core capabilities without a full enterprise implementation.
That includes:
- Microfinance banks looking to replace ageing systems, improve visibility or build stronger digital capabilities.
- Digital lenders that need a banking core to manage customer accounts, lending activity and integrations.
- Fintech platforms that need API-driven connectivity to regulated financial infrastructure.
- Cooperatives and financial societies moving from spreadsheets or limited systems toward a structured financial platform.
For a large commercial bank with complex product structures and deeper configuration requirements, full SeaBaas is the more appropriate core system. This distinction helps institutions avoid buying more complexity than they need.
Questions to Ask When Comparing MFB Core Banking Systems
Once the differences are clear, the next step is to test each vendor against your actual operation.
When evaluating Seabaas Lite and other mfb core banking systems, ask:
- Can the platform support our current deposit and lending products?
- How difficult will it be to connect our mobile app, payment rails and other services?
- Which regulatory reports come with the platform?
- What manual reconciliation will remain after implementation?
- Where will our data be hosted?
- What infrastructure will our team still need to manage?
- How does data migration work?
- What support do we receive during implementation and after go-live?
- How are incidents escalated?
- Which activities can our administrators manage themselves?
- What happens as customer and transaction volumes increase?
- What is the full cost over the next few years?
The quality of the answers matters more than the length of the vendor’s feature list.
Frequently Asked Questions
What is SeaBaas Lite?
SeaBaas Lite is a streamlined SaaS core banking platform from Peerless. It is designed for microfinance banks, digital lenders, fintech platforms, cooperatives and growing financial institutions.
Is SeaBaas Lite different from SeaBaas?
Yes. SeaBaas provides deeper modularity and configuration for complex financial institutions and commercial banks. SeaBaas Lite packages essential core capabilities into a more standardised SaaS deployment for smaller and growing institutions.
Is SeaBaas Lite API-first?
Yes. SeaBaas Lite retains the API-first integration architecture of SeaBaas and supports connectivity to digital channels, payment infrastructure, identity services, credit bureaus and other approved systems.
Can SeaBaas Lite support Nigerian MFB regulatory reporting?
SeaBaas Lite includes pre-configured reporting templates aligned with local regulatory requirements for its Nigerian market deployment. Institutions should confirm their specific reporting requirements during implementation.
Is SeaBaas Lite cloud-based?
Yes. SeaBaas Lite is delivered as a managed SaaS offering. Its Nigerian deployment uses cloud infrastructure with Nigerian data residency.
How long does SeaBaas Lite implementation take?
The streamlined implementation model can move toward go-live from approximately week five onward. The actual timeline depends on the institution’s data, integrations, scope and internal readiness.
Is SeaBaas Lite suitable for a growing MFB?
SeaBaas Lite was designed for growing financial institutions. An institution should still evaluate expected customer volumes, transaction demand, integrations and product requirements before selecting the appropriate deployment.
Conclusion
Comparing SeaBaas Lite to other MFB core banking systems starts with identifying the operational drag the institution needs to drop. When staff spend hours on manual reconciliation or standard reports take days to compile, you must measure the true cost of that effort. If every new integration turns into a bespoke technical project, the underlying architecture is actively working against the business. Include that friction in your vendor assessment.
SeaBaas Lite provides a managed SaaS core built on API-first connectivity, essential banking operations, and locally grounded technical support. It fits best with institutions that want modern capabilities without the massive overhead of a full enterprise deployment. For an MFB considering a migration, the ultimate evaluation comes down to daily execution. You have to ask what banking operations will actually look like after go-live, and whether the new core makes it easier to run the institution you are trying to build.
Evaluating a new core banking system for your MFB?
Speak with the Peerless team about SeaBaas Lite and assess your current infrastructure, data, integrations, reporting requirements and migration readiness before making a core banking decision.