
Islamic banking does not begin with a product name. It begins with a contract, and that contract defines how money moves, how assets are treated, how profit is earned, how risk is shared, how customers are obligated, and how the institution proves that the product follows approved Sharia principles.
This is why Islamic finance contracts matter to product teams, operations teams, finance teams, Sharia reviewers, and technology leaders. If the system does not understand the contract behind a product, the bank will eventually rely on manual explanations, approval notes, spreadsheets, and after-the-fact review.
At Peerless, this is one of the reasons we built Mizan – a purpose-built digital banking core designed for Islamic and non-interest financial institutions. It maps Islamic finance contracts at product creation, so each product starts from the right structure before it enters daily banking operations.
What Are Islamic Finance Contracts?
Islamic finance contracts are the approved structures that define how an Islamic or non-interest financial product should work. They are not labels but they determine the commercial substance of the transaction.
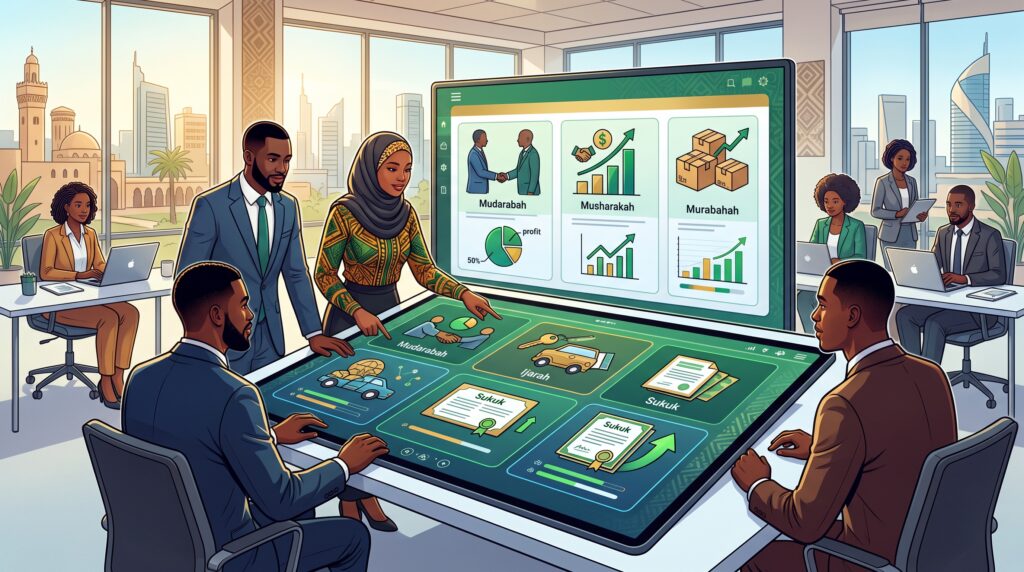
For example, a Murabaha product follows a cost-plus sale structure. An Ijara product follows a lease structure. Mudarabah follows a profit-sharing arrangement. Musharakah involves partnership participation. Istisna supports manufacture or construction-related financing. Each contract has its own treatment for ownership, profit, risk, documentation, accounting, reporting, and review.
That is why Islamic banking becomes difficult when the core banking system treats every product like a variation of a conventional loan or deposit. Product names may look correct, but the underlying behaviour may still create problems. A strong Islamic core should connect product setup to the right contract from the beginning.
Why Contract Mapping Matters in Core Banking
Contract mapping is the process of linking a banking product to its approved Islamic finance contract inside the core system.
This matters because every downstream activity depends on that foundation. Product configuration, customer documentation, approval workflows, asset tracking, profit calculation, GL posting, reporting, and audit review all need to follow the contract logic.
Without proper contract mapping, teams may face avoidable problems:
| Problem Area | What Can Go Wrong |
|---|---|
| Product setup | Islamic products may behave like conventional products beneath the interface. |
| Operations | Teams may need manual checklists to enforce contract steps. |
| Finance | Profit, penalties, and postings may require extra reconciliation. |
| Sharia review | Reviewers may struggle to trace the product from approval to execution. |
| Reporting | Reports may need manual reconstruction from multiple sources. |
Mizan approaches this differently. At product creation, every product must map to a valid Islamic contract. This helps the institution treat Islamic finance contracts as part of the core operating model, not an extra layer handled outside the system.
Murabaha: Cost-Plus Sale Financing
Murabaha is one of the most common Islamic finance contracts. It is typically used for asset financing where the institution purchases an asset and sells it to the customer at a disclosed markup.
For a Murabaha product to work properly, the system should help the bank manage the asset request, purchase evidence, supplier details, disclosed cost, markup, repayment schedule, customer obligation, and ledger treatment.
The sequence matters. The institution should not treat Murabaha like a cash loan with markup added afterward. The asset purchase and ownership flow form part of the transaction’s substance.
In Mizan, Murabaha can be configured as a first-class product type with its own accounting treatment, disclosure fields, and profit mechanics. Asset-backed workflow support also helps teams track the asset journey before deal booking and posting.
For operations teams, this reduces the risk of missing important asset evidence. For Sharia reviewers, it creates a clearer trail from product setup to transaction execution.
Ijara: Lease-Based Financing
Ijara is a lease-based contract. The institution owns or holds the asset and leases it to the customer for an agreed rental amount over a defined period.
In practice, Ijara requires careful asset handling. The bank must manage the asset record, rental schedule, ownership status, residual value, payment history, and end-of-term transfer where applicable.
A weak core setup can push asset details outside the system. That creates pressure during reconciliation, audit, and Sharia review.
Mizan supports Ijara configuration with asset tracking and schedule customization. This helps teams manage lease-related activity inside the core flow, instead of relying only on scattered documents and manual records.
For Islamic banks that want to scale lease-based products, the value is straightforward: better asset visibility, cleaner product control, and stronger review evidence.
Mudarabah: Profit-Sharing Investment
Mudarabah is a profit-sharing contract where one party provides capital and another party manages the investment activity.
In banking, Mudarabah often applies to investment accounts and pool-based profit distribution. The bank may act as Mudarib, while customers provide funds into approved pools.
This contract places serious responsibility on profit calculation. The institution must explain how funds entered each pool, how income was allocated, which ratios applied, what the bank retained, and how customers received their share.
Mizan supports pool-based Mudarabah profit distribution. Deposits can be assigned to defined pools. Each pool can track balances, weightages, tenor categories, utilization, gross profit, Mudarib share, and depositor allocation.
This helps finance teams reduce spreadsheet dependence in a sensitive area. It also gives Sharia reviewers and management a more reliable basis for checking the numbers.
Musharakah: Partnership-Based Financing
Musharakah is a partnership contract where the parties contribute capital and share profit according to agreed terms. Losses are usually borne according to capital contribution, subject to the approved structure.
Banks may use Musharakah for joint venture-style arrangements or diminishing partnership structures, depending on their product strategy and Sharia governance framework.
For a core banking system, Musharakah requires more than a repayment calendar. The system should help track capital contribution, ownership share, profit allocation, loss treatment, and changes over time.
Mizan supports Musharakah as one of the Islamic finance contracts that can be modelled at product creation. This gives the institution a stronger way to configure partnership-based financing with the right operational and accounting treatment.
Istisna: Manufacture and Construction Financing
Istisna is commonly used for assets that need to be manufactured, constructed, or delivered later. It can apply to areas such as equipment, property, infrastructure-related financing, or other approved use cases.
This contract needs careful milestone management.
The bank may need to track specifications, progress, drawdowns, delivery conditions, customer obligations, and profit recognition linked to the agreed structure.
If the core system does not support this properly, teams may handle critical details outside the core. That makes review harder and increases the risk of incomplete evidence.
Mizan supports Istisna as part of its native Islamic product coverage. For banks that finance manufactured or constructed assets, this gives product and operations teams a cleaner way to manage transaction progress from booking to closure.
Qard Hassan: Benevolent Loan
Qard Hassan is a benevolent loan structure where the customer repays the principal without a return to the lender.
Because of this, the system must keep the accounting treatment clean. It should not accidentally apply income logic, interest accrual, or charges that conflict with the approved structure.
Mizan supports Qard Hassan with principal-only treatment and dedicated accounting handling. It can also support charity-fund routing where accidental accruals or non-compliant income need separate treatment under Sharia supervision.
This matters because some risks are small in transaction value but serious in governance effect. A system should help the bank prevent the wrong treatment before it reaches the ledger.
Other Islamic Finance Contracts Banks May Need
Beyond the commonly used structures above, some institutions may require support for other Islamic finance contracts, depending on their market, product roadmap, and Sharia approvals.
These may include:
| Contract | What It Generally Supports |
|---|---|
| Salam | Advance payment transactions where delivery occurs later under approved terms. |
| Wakala | Agency-based arrangements where one party acts on behalf of another. |
| Tawarruq | Commodity-based structures used in some Islamic finance markets, subject to Sharia governance. |
| Sukuk investment book | Management of Islamic investment instruments where relevant to the institution. |
| Takaful integration | Connectivity with Islamic insurance-related products or partners where required. |
Not every institution will need every contract immediately. The important thing is to choose a core that can support Islamic finance contracts with proper structure as the bank grows.
How Mizan Maps Contracts at Product Creation
Mizan treats contract mapping as a core part of product setup.
When your team creates a product, the system connects it to the relevant Islamic finance contract. That contract basis then influences configuration, workflow, asset handling, profit treatment, approvals, posting, and reporting.
The practical effect is important.
Product teams get clearer boundaries during setup. Operations teams can follow a workflow that reflects the approved structure. Finance teams work from cleaner ledger logic. Sharia reviewers can trace how the product moved from approval to execution.
This approach also helps prevent common issues that arise when Islamic products run on conventional systems, such as hidden interest logic, weak asset-backing validation, poor pool segregation, and manual profit calculation.
Mizan’s goal is to help institutions reduce structural Sharia risk by making compliance part of the system’s behaviour.
What Banks Should Ask Before Configuring Islamic Products
Before launching or reviewing Islamic finance products, leaders should ask practical questions about how the core handles each contract.
| Evaluation Area | Question to Ask |
|---|---|
| Contract mapping | Does every product connect to a valid approved Islamic finance contract? |
| Product behaviour | Does the system follow the contract logic after configuration? |
| Asset flow | Can the core track asset purchase, receipt, ownership movement, and customer obligation where required? |
| Profit distribution | Can the system calculate and explain pool-based profit allocation? |
| Penalty treatment | Can non-compliant income or penalties follow approved handling? |
| Ledger posting | Can the core block restricted postings before they enter the ledger? |
| Audit trail | Can Sharia reviewers trace product setup, approval, transaction activity, and posting history? |
| Reporting | Can reports come from source system records without heavy manual reconstruction? |
If the answers are unclear, the institution may be asking people to compensate for system weakness.
Where Mizan Fits
Mizan was built for Islamic and non-interest financial institutions that need stronger control over how products are created and run.
It supports key Islamic finance contracts, including Murabaha, Ijara, Mudarabah, Musharakah, Istisna, and Qard Hassan. It also supports other structures and integrations relevant to Islamic banking, depending on the institution’s requirements.
With Mizan, contract mapping starts at product creation. Asset-backed financing can follow clearer workflows. Profit distribution can run through defined pools. Sharia validation can happen before ledger posting. Audit trails help reviewers work from system evidence.
For banks, this creates a stronger foundation for daily execution and future growth.
Conclusion
Islamic finance contracts are the foundation of Islamic and non-interest banking products.
When a core banking system does not understand those contracts, the bank may still launch products, but teams will carry the burden through manual checks, spreadsheet calculations, separate evidence files, and repeated explanations during review.
That model becomes harder to manage as the institution grows.
Mizan gives Islamic and non-interest financial institutions a core designed around the substance of Islamic finance. It maps products to valid contracts, supports asset-backed workflows, handles pool-based profit distribution, strengthens audit evidence, and helps transactions follow the right structure before they reach the ledger.
For a broader view of why this requires purpose-built infrastructure, read our guide on why Islamic banks need a purpose-built Islamic core banking system.
You can also book a session with our Mizan experts to see how your institution can configure Islamic finance contracts with stronger control, clearer evidence, and better operational confidence.